Arrow Exploration – Record Production, Surging Profits and Plenty More Wells to Come
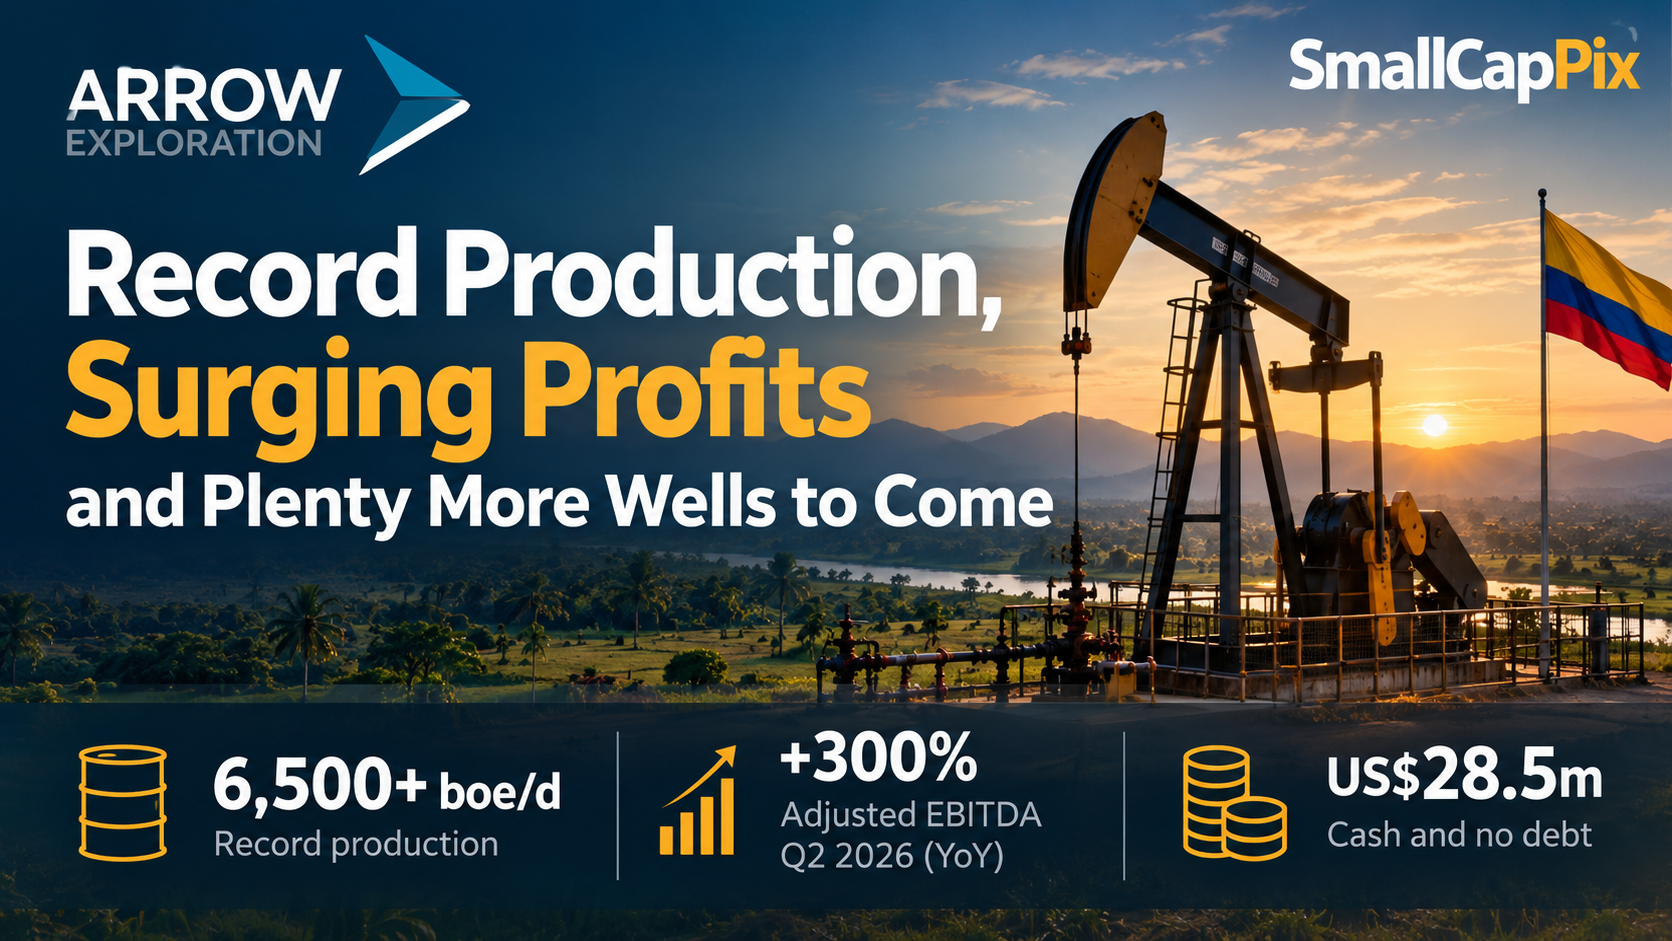
Arrow Exploration has developed into one of AIM’s more interesting small-cap oil growth stories, combining rapidly rising production with strong cash generation, a debt-free balance sheet and an expanding reserve base. With production now exceeding a record 6,500 boe/d and further wells to come, the growth story may have further to run.
Arrow Exploration (AIM/TSXV: AXL) caught our attention at SmallCapPix following a set of financial results that demonstrated just how quickly the economics of the business are improving.
And the operational story has continued to move forward.
On 22 October, Arrow announced that corporate production had surpassed a record 6,500 barrels of oil equivalent per day (boe/d), up from more than 6,000 boe/d reported only last month.
Behind those headline numbers sits an increasingly interesting small-cap oil producer with strong margins, significant cash generation, no debt and an active drilling programme.
What Does Arrow Exploration Do?
Arrow is an oil and gas producer focused principally on Colombia, alongside producing assets in Canada.
The centrepiece of the portfolio is the Tapir Block in Colombia’s prolific Llanos Basin, where Arrow has a 50% beneficial interest.
Tapir covers more than 65,000 gross acres and includes producing fields such as Carrizales Norte, Rio Cravo Este, Alberta Llanos, Mateguafa and, most recently, Icaco.
Importantly, Arrow is no longer dependent upon a single discovery.
Carrizales Norte has already developed into an important producing field, Mateguafa has emerged as another production centre following successful drilling based upon 3D seismic, while Icaco — discovered in Q2 2026 — is rapidly becoming the next major development area.
Arrow also owns Canadian producing assets, including the recently acquired Thorsby property in Alberta, alongside its existing Fir and Pepper interests.
Icaco – The Latest Growth Engine
Icaco is perhaps the most exciting part of the portfolio today.
The field was discovered in May 2026 when Icaco-1 encountered hydrocarbons across several formations. Arrow subsequently moved quickly into development drilling.
This ability to turn exploration success into production relatively quickly is central to the Arrow investment case. Successful wells generate additional cash flow which can then help finance further drilling.
By September, Arrow was planning another five wells at Icaco, with a further five-well programme contingent upon results — potentially taking development to 15 oil wells plus a water disposal well.
That programme is now translating directly into higher production.
The Financial Numbers Stand Out
It was Arrow’s Q2 2026 financial results that particularly caught our attention.
For the three months ended 30 June, Arrow reported:
-
US$34.2m revenue net of royalties, up 116% from US$15.9m
-
US$25.1m adjusted EBITDA, up approximately 300% from US$6.3m
-
US$10.4m net income, versus a US$0.9m loss a year earlier
-
US$18.9m funds flow from operations
-
US$15.7m operating cash flow
-
US$63.42/boe realised corporate operating netback
-
US$28.5m cash
-
No debt
Average Q2 production increased 30% year-on-year to 4,902 boe/d, compared with 3,768 boe/d during Q2 2025.
That operational leverage is worth highlighting.
Production increased 30%, but revenue increased 116% and adjusted EBITDA increased around 300%.
That's exactly the kind of earnings acceleration we look for when screening smaller growth companies.
It also demonstrates that Arrow isn't simply drilling wells to produce impressive production headlines. Those additional barrels are translating into substantial EBITDA, profits and cash flow.
And unlike many junior producers, Arrow is currently pursuing its growth strategy from a strong balance sheet rather than carrying significant debt.
A Rapidly Expanding Reserve Base
September brought another important development.
An independent mid-year reserves evaluation showed substantial increases across Arrow's reserve categories.
1P reserves increased 110% to 11.4 MMboe, while 2P reserves increased 82% to 21.4 MMboe and 3P reserves increased 71% to 34.4 MMboe.
The corresponding pre-tax NPV10 valuations were:
1P – US$193m
2P – US$410m
3P – US$731m
The increases were driven principally by the Icaco discovery, continued development at Mateguafa and the acquisition of Thorsby.
This is significant because Arrow isn't simply increasing production by running down its existing reserves. Successful drilling and acquisition activity have simultaneously expanded the amount of recoverable hydrocarbons attributed to the business.
Today's Update – Another Production Record
Today's announcement provides further evidence of that momentum.
Arrow announced that corporate production has now exceeded a record 6,500 boe/d, compared with average production of 4,902 boe/d during Q2.
The latest increase has been supported by new Icaco-7 and Icaco-8 production.
Icaco-8 commenced production on 12 October and is currently producing 1,204 bopd gross, equivalent to approximately 602 bopd net to Arrow, from the Carbonera C7 formation.
Importantly, the well is currently being produced at a restricted rate while clean-up continues.
Drilling encountered 72 feet of measured net oil pay in the C7, together with additional oil-bearing intervals in the Guadalupe, Lower Gacheta and Ubaque formations.
Icaco-7, meanwhile, commenced production during September and is currently producing 248 bopd gross, or approximately 124 bopd net to Arrow, from the Ubaque.
Once again, Icaco appears to be demonstrating the multi-zone potential of the discovery.
More Catalysts to Come
What makes the production record particularly interesting is that Arrow hasn't finished drilling.
Further Icaco wells provide potential near-term production catalysts, while additional development opportunities remain across Mateguafa, Carrizales Norte, Rio Cravo Este and Alberta Llanos.
Another important catalyst is the Tapir licence extension.
Arrow has continued discussions with the relevant authorities and management has stated that it believes the extension will ultimately be awarded to Arrow and its partner.
This matters because the independent reserves assessment treats the licence duration differently across its reserve categories. The 1P case assumes the existing February 2028 expiry, while 2P assumes the first five-year extension and 3P assumes a second five-year extension.
Securing the extension would therefore remove an important area of uncertainty surrounding the longer-term value of Tapir.
What Are the Risks?
Arrow remains exposed to oil prices, meaning weaker commodity prices would affect revenues, cash generation and potentially the economics of future drilling.
There is also drilling and execution risk. Recent results have been impressive, but future wells cannot be assumed to replicate that success.
Colombia introduces jurisdictional and regulatory risk, while the Tapir licence extension remains outstanding.
Reserve NPV figures should also not be confused with cash or market value. They are estimates based upon assumptions around future commodity prices, costs, production profiles and licence duration.
The SmallCapPix Take
Arrow Exploration is increasingly looking less like a speculative junior oil company and more like a genuine small-cap production and earnings growth story.
The financial acceleration is particularly striking.
A 30% year-on-year increase in Q2 production accompanied a 116% increase in revenue and an approximately 300% increase in adjusted EBITDA, while Arrow generated US$15.7m of operating cash flow and ended June with US$28.5m cash and no debt.
Since then, the operational story has continued moving forward.
Production has now surpassed 6,500 boe/d, Icaco continues to deliver successful wells, 2P reserves have increased to 21.4 MMboe, and further drilling provides a visible sequence of potential catalysts.
There are risks — notably oil prices, drilling execution and the Tapir licence extension — but there is something particularly attractive about the Arrow story:
The company doesn't need investors to imagine what successful drilling might eventually look like. It is already translating the drill bit into barrels, barrels into cash flow, and cash flow into the next phase of growth.
That makes Arrow Exploration one we think is well worth having on the watchlist.